
Adding another physician to your practice can help you serve more patients and share the responsibilities of running the business. But as a co-owner, you may have a more personal concern: could another physician’s malpractice put you at risk simply because you own the same medical practice?
This is where corporation liability protection becomes important. A properly formed California professional medical corporation may help limit your personal exposure when a colleague faces a malpractice claim. However, it does not protect you from liability for your own professional conduct or other independent obligations.
Understanding those limits can help you see why corporate liability protection and malpractice insurance serve different roles. This guide explains how the two work together, when you may still face personal liability, and why properly forming and maintaining your medical corporation matters.
Key Takeaways
- A medical corporation may help limit exposure based solely on another physician’s malpractice, but it does not remove responsibility for your own conduct.
- Corporation liability protection may help separate you from liabilities arising solely from a colleague’s malpractice, while malpractice insurance provides coverage for professional liability claims subject to the terms and limits of the policy.
- Your corporation’s ownership, bylaws, shareholder agreements, and business operations should comply with California law and applicable Corporate Practice of Medicine (CPOM) requirements. Separately, maintaining distinct finances, contracts, records, and decision-making helps preserve the corporation’s separate legal identity. Neither type of compliance guarantees that a court will reject every attempt to impose personal liability.
- Review the structure before adding another physician, changing ownership, or relying on older corporate documents.
How Physicians Gain Corporation Liability Protection in California?
If you operate a private medical practice in California, forming a professional medical corporation can create a legal entity separate from you as an individual shareholder. California’s professional corporation laws allow licensed physicians to organize their practices through this structure, subject to applicable ownership, licensing, and Corporate Practice of Medicine requirements.
That separation is the foundation of corporation liability protection. When the corporation is properly formed and maintained, liabilities belonging to the medical practice or arising from another physician’s conduct do not necessarily become your personal liabilities simply because you co-own the corporation.
The protection is not absolute. Your own professional conduct, supervision, contractual obligations, or other independent duties can still create personal exposure. Understanding that distinction is especially important when another physician in your practice faces a malpractice claim.
What Corporation Liability Protection Can and Cannot Do?
When you form a professional medical corporation, it operates as a legal entity separate from you and the other physician-shareholders. In practical terms, the corporation can enter contracts, incur business obligations, and conduct the practice’s business in its own name rather than treating every corporate obligation as the personal obligation of each shareholder.
This distinction becomes especially important when a colleague faces a malpractice claim. If another physician in your medical practice is sued for malpractice, owning the same professional medical corporation does not, by itself, mean that you are personally responsible for that physician’s care. You may still face personal liability based on your own medical care, supervision, involvement, contractual obligations, or other independent duties.
The professional medical corporation, however, may still be liable for the treating physician’s conduct under employment or agency principles, and corporate assets may be available to satisfy a judgment.
This protection is limited and fact-specific. It does not guarantee that a physician will never be named in a claim, and it does not erase an independent duty created by the physician’s own actions, supervision, contracts, or guarantees.
Three Layers of Protection and Responsibility in a Medical Practice
To understand where your personal exposure may begin and end, it helps to separate the roles of the physician, the professional medical corporation, and malpractice insurance:
1. The individual physician
Each physician remains personally responsible for their own professional negligence, decisions, misconduct, and other duties personally owed. A physician does not become personally liable for a corporate tort merely because the physician is also a shareholder, officer, or director.
2. The professional medical corporation
The corporation operates the practice, enters agreements, receives revenue, engages licensed professionals, and may face claims related to its operations. It may also be vicariously liable for malpractice committed by an employee or agent acting within the scope of that relationship.
3. The insurance policy
Insurance may provide defense and payment for covered claims, subject to its insured parties, limits, exclusions, reporting requirements, and other terms.
These layers may work together, but they do not perform the same function.
Does a Medical Corporation Protect You From a Colleague’s Malpractice?
Imagine that you and another physician own shares in the same corporation. Your colleague treats a patient and later faces a malpractice allegation. You did not treat the patient or participate in the disputed decision.
Being a co-owner of the same professional medical corporation does not automatically make you personally liable for a colleague’s malpractice. However, you could still be named in a malpractice lawsuit, and forming a corporation does not guarantee that you will avoid personal liability in every case.
Whether you may be personally liable in a malpractice claim depends on the specific circumstances, including who provided the care, your involvement or supervisory responsibilities, the duties each physician assumed, and the relationship between the physicians and the professional medical corporation.
Liability for Your Own Professional Care
A corporation does not eliminate personal liability for medical malpractice arising from your own care. If a claim concerns your diagnosis, treatment, advice, documentation, supervision, or another duty personally attributed to you, incorporation does not protect you from liability for your own professional negligence or other tortious conduct.
That is one reason physicians continue to need appropriate professional liability insurance after incorporating.
Liability Arising From Another Physician’s Care
Even if you’re a physician-shareholder in a professional medical corporation, you’re not automatically considered a treating physician simply because you own part of the same practice. If another physician provided the care and you had no involvement in it, your shared ownership alone does not necessarily make you personally responsible for that physician’s malpractice.
Your potential liability may change, however, if you were personally involved in the patient’s care or had another duty connected to it. Personal exposure may arise if you participated in the patient’s care, personally undertook and negligently performed a supervisory duty, authorized or directed tortious conduct, or otherwise breached a duty you personally owed.
Merely serving as a shareholder, officer, or director—or merely working for the same corporation—does not by itself establish personal liability. This is why your actual involvement and responsibilities matter—not simply the percentage of the corporation you own.
Why the Corporation May Still Face a Claim
Even when you are not personally responsible for a colleague’s malpractice, the professional medical corporation itself may still be named in a claim. The corporation operates the medical practice and may have responsibilities connected to employment, supervision, staffing, policies, contracts, or other aspects of the practice’s operations.
For example, the corporation may be vicariously liable when the treating physician was its employee or agent acting within the scope of that relationship. It may also face direct claims involving negligent hiring, retention, supervision, staffing, or practice policies. Whether the corporation is ultimately liable depends on the specific facts and applicable law.
In other words, the corporate structure may help separate you from liabilities that belong to the practice or another physician, but it does not make the professional medical corporation immune from being sued. A judgment against the corporation does not automatically become a personal judgment against its shareholders, but it may be collected from corporate assets and may therefore reduce the value of every shareholder’s interest in the practice.
Other Situations That Can Create Personal Liability
Limited liability does not mean no liability. The corporation is one layer of medical practice liability protection, but your actions and personal obligations still matter.
Personal Guarantees and Other Obligations
Physician owners sometimes personally guarantee leases, loans, equipment financing, or other business agreements. Those promises may remain personal even though the contract benefits the corporation.
Employment, wage, tax, licensing, and regulatory obligations may also require separate analysis from a malpractice claim.
When Courts May Challenge Your Medical Corporation’s Separate Existence
Your professional medical corporation should operate as a genuine business entity separate from your personal activities as a shareholder.
In some circumstances, a court may examine the relationship between your corporation and its shareholders when deciding whether to respect the corporation’s separate existence. California alter-ego liability generally requires both a unity of interest between the corporation and the shareholder and circumstances in which respecting the corporation’s separate existence would produce an inequitable result.
Relevant factors may include commingling or diversion of funds, treating corporate assets as personal assets, inadequate capitalization, disregard of corporate formalities, ownership records, separate finances, documented decisions, and how you actually operate the business.
A single missing document does not automatically determine the outcome. The broader question is whether you and the other shareholders consistently operate the corporation as a separate legal entity.
Malpractice Insurance and Corporate Protection Serve Different Purposes
No, malpractice insurance and a professional medical corporation do not perform the same function. Malpractice insurance and corporate protection should be reviewed together, but neither replaces the other.
What Corporate Liability Protection Does
When your professional medical corporation is properly formed and maintained, it creates legal separation between you as an individual shareholder and the corporation operating the medical practice. That separation may help protect your personal assets from certain liabilities belonging to the corporation or arising from a colleague’s conduct simply because you co-own the practice.
However, corporate liability protection does not prevent every malpractice claim from reaching you personally. You can still face liability for your own medical care, direct involvement, supervision, or other duties you personally assume. This is where malpractice insurance provides a second and different layer of protection.
What Malpractice Insurance Does
Malpractice insurance addresses professional liability risk differently from the corporation itself. Depending on the terms of the policy, coverage may provide defense and payment for covered malpractice claims involving an insured physician. The practice should also confirm whether the professional medical corporation is itself an insured and whether the policy includes appropriate entity or vicarious-liability coverage.
The key distinction is that your medical corporation creates legal separation; malpractice insurance provides financial protection for covered claims. A properly structured practice may therefore rely on both rather than treating either one as a complete substitute for the other.
Why Your Corporate Structure and Insurance Coverage Should Align?
Your corporate documents and malpractice coverage should reflect how your practice actually operates. If physicians join or leave the practice, ownership changes, or professional roles change, outdated corporate documents or insurance arrangements may no longer accurately reflect those relationships.
Corporate compliance cannot replace malpractice insurance, and insurance cannot correct an improperly structured medical corporation. Keeping both aligned with the actual practice helps each layer of protection serve its intended role.
Review your corporate structure when the practice changes, and separately review your malpractice coverage with a qualified insurance professional to determine whether the insured parties and coverage remain appropriate.
How Proper Medical Corporation Formation Supports Liability Protection
Properly forming your professional medical corporation helps establish the legal and organizational separation needed for corporation liability protection. While proper formation does not guarantee the outcome of a future malpractice claim, following California’s formation, ownership, and governance requirements helps establish the corporation as a separate legal entity.
Your corporate documents should reflect how your practice actually operates. They may need to be reviewed when you add a shareholder, bring in another physician, open a new location, or change your management structure.
Articles and Bylaws Help Establish and Govern Your Medical Corporation
Your articles of incorporation establish the professional medical corporation’s legal existence and identify the professional purpose and other required information for the entity being formed. Your bylaws then establish the internal rules for operating the corporation, including matters involving shareholders, directors, officers, meetings, voting, and corporate records.
Keeping these documents consistent with your actual practice helps demonstrate that your medical corporation is being operated as the separate entity it was formed to be.
Our guide to professional medical corporation bylaws provides more detail on these internal governance rules.
Shareholder Agreements Address the Business Relationship
A medical corporation shareholder agreement may address transfers, departures, disability, death, valuation, voting, buyouts, and dispute procedures.
It can also clarify how physician owners divide administrative responsibilities. However, an agreement between shareholders cannot eliminate a duty imposed by law or guarantee how a patient’s claim will be resolved.
Ownership Records Should Match Reality
Share issuances, transfers, ownership percentages, and officer appointments should be documented correctly. The people identified in the records should match the people who actually own and control the practice.
Informal promises of future ownership can create uncertainty when a colleague believes they have already become a partner but the corporate records say otherwise.
How Ownership and CPOM Rules Affect a Medical Corporation
A California medical corporation cannot be owned or controlled like an ordinary company with any combination of investors and managers.
If you own a California professional medical corporation, California-licensed physicians must collectively own more than 50% of the total number of shares. The specifically authorized allied health professionals listed in California Corporations Code Section 13401.5 may collectively own no more than 49% of the shares, and the number of allied-professional shareholders may not exceed the number of physician shareholders. An unlicensed person cannot own shares in the medical corporation.
Our ownership guide explains who can own a professional medical corporation in California and how ownership restrictions affect physicians and other licensed professionals.
Clinical Control Must Remain With Physicians
The corporate practice of medicine doctrine concerns more than the percentage of shares each person owns. The physician-controlled practice must retain ultimate authority over clinical judgment and other decisions California reserves to licensed physicians, including patient-care decisions and specified matters involving medical records, clinical staffing, payer relationships, coding and billing, and medical equipment.
An unlicensed manager or management services organization may provide administrative assistance, but authority over decisions reserved to licensed physicians cannot be delegated to an unlicensed person. Additional statutory restrictions apply when a private equity group or hedge fund is involved with the practice, including California Health and Safety Code Sections 1190 through 1192, effective January 1, 2026.
Review the Structure Before Adding a Colleague
Before offering shares or control to another provider, confirm:
- Whether the person holds an eligible professional license
- What percentage they may own
- Whether they will serve as a director or officer
- Which professional and business decisions they may control
- How their interest may be transferred later
- What happens if they leave, retire, die, or lose their license
These issues are easier to address before ownership begins than after a dispute or malpractice claim arises.
How Noncompliance Can Create Corporate, Regulatory, and Liability Risks
Forming a professional medical corporation is only the beginning. Failure to follow California ownership and Corporate Practice of Medicine requirements can create licensing, regulatory, governance, and enforceability problems. Separately, failing to operate the corporation as a genuine entity distinct from its shareholders may support an alter-ego claim under the circumstances described above. A CPOM or ownership violation does not, by itself, automatically establish alter-ego liability.
This is why proper formation and ongoing compliance matter when you practice with other physicians. Your ownership records, governing documents, finances, and actual business operations should consistently reflect how your professional medical corporation is structured and operated.
Keep Governance and Ownership Records Current
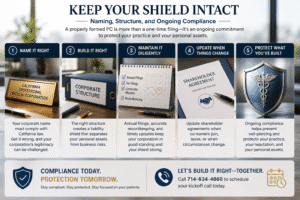
Maintain the adopted bylaws, ownership records, initial actions, and documentation of significant corporate decisions.
Update the records when the practice admits a shareholder, changes officers, enters a major agreement, opens another location, or materially changes its operations.
Maintain Separate Business Operations
Use financial accounts, contracts, invoices, payroll systems, and records that identify the corporation. Avoid treating corporate funds as the personal funds of a shareholder.
People signing agreements should also make clear whether they are signing for the corporation or in an individual capacity.
Review Changes in Owners, Services, and Insurance
A shareholder’s departure, retirement, death, license problem, or transfer of shares may affect whether the ownership remains compliant.
Adding a physician, specialty, location, or service may also change insurance needs. The corporation’s documents, operating relationships, and policies should describe the same business.
What Should You Review Before Adding a Colleague?
Before another physician joins your practice, review whether your corporate structure still reflects how the practice will operate. Important areas include:
- Current articles, bylaws, and ownership records
- Ownership eligibility and share percentages
- Shareholder or buy-sell agreements
- The new physician’s role as an owner, employee, or independent contractor
- Clinical and administrative responsibilities
- Malpractice insurance arrangements
- Any changes needed to corporate records or governing documents
Reviewing these areas before the relationship begins can help identify inconsistencies that could create compliance or liability concerns later.
How a Business Lawyer Can Help Protect Your Medical Practice
Whether you are forming a new professional medical corporation or adding physicians to an existing practice, the corporate structure should reflect how the business will actually operate. Ownership, governing documents, professional relationships, insurance arrangements, and ongoing corporate compliance all play a role in maintaining the separation the corporation is intended to provide.
An experienced business attorney can help you form the corporation correctly from the beginning or review an existing corporation before ownership or practice arrangements change. This may include reviewing ownership eligibility, articles and bylaws, shareholder arrangements, corporate records, and other structural issues that could affect the practice.
If your corporation was originally formed for one physician, adding another physician does not necessarily mean starting over. A legal review can help determine whether the existing structure remains appropriate and identify documents or corporate records that should be updated before the new arrangement begins.
Our guide on how to form a professional medical corporation in California explains the major formation and organizational components involved.
Incorporation Attorney helps California physicians form and maintain professional medical corporations designed around their actual practice structure. Schedule a kick-off call to discuss forming a new medical corporation or reviewing your existing corporation before bringing another physician into the practice.
Frequently Asked Questions About Corporation Liability Protection
Am I personally liable if another physician in my medical corporation commits malpractice?
Not automatically simply because you own shares in the same corporation. A properly structured corporation may help limit personal exposure based solely on another physician’s conduct.
Your own involvement, supervision, guarantees, agreements, and independent duties may still matter. The corporation may also face a claim connected to the physician or practice.
Does a professional medical corporation protect me from my own malpractice?
No. A corporation does not protect a physician from liability for the physician’s own professional negligence or other tortious conduct.
Physicians remain responsible for their personal conduct and need professional liability insurance appropriate to their services. This is an important limit on professional corporation malpractice liability.
Does a medical corporation replace malpractice insurance?
No. The corporation establishes the legal and ownership structure of the practice. Insurance responds to covered claims according to the policy.
A physician practicing through a professional medical corporation should maintain both a compliant entity structure and insurance that accurately reflects the physicians, the corporation, its services, and its professional relationships.
Can an employed physician’s malpractice expose the professional medical corporation?
The corporation may be vicariously liable for malpractice committed by an employed physician acting within the scope of employment and may also face direct claims based on its own conduct. Agency, practice policies, hiring, retention, supervision, and other facts may affect the analysis.
That does not automatically make every shareholder personally responsible for the employed physician’s conduct. Shareholder, officer, or director status alone is insufficient; personal liability ordinarily requires the shareholder’s own tortious conduct, breach of an independently owed duty, a personal contractual undertaking, a statute imposing individual liability, or a basis for alter-ego liability.
How do I prepare my medical corporation for another shareholder or physician?
Before another physician joins your medical corporation, review whether your current documents and records reflect the practice as it operates today and the relationship you plan to establish.
This review may include ownership eligibility, share issuance, governance, contracts, insurance, supervision, and the responsibilities the incoming physician will assume.
Should Physicians in the Same Corporation Carry Separate Malpractice Policies?
Whether physicians in the same professional medical corporation need separate malpractice policies depends on the practice’s insurance arrangements and coverage terms. Corporate liability protection does not replace malpractice insurance, so review the practice’s coverage with a qualified insurance professional to determine who is insured and whether separate coverage is needed.
Protect Your Medical Practice With the Right Corporate Structure
Corporation liability protection can be an important part of practicing alongside other physicians, but it does not eliminate every source of personal liability. A properly formed and maintained professional medical corporation may help separate you from liabilities arising solely from a colleague’s malpractice, while you remain responsible for your own professional conduct and other duties you personally assume.
That protection works best as part of a broader risk-management structure. Your corporation should follow California ownership and Corporate Practice of Medicine requirements, maintain appropriate governing documents and records, operate as a separate entity, and work alongside appropriate malpractice insurance.
Whether you are forming a new professional medical corporation or reviewing an existing practice before adding another physician, Incorporation Attorney can help you evaluate the corporate structure and documents supporting your practice. Schedule a kick-off call or contact us to discuss your next steps.